Request a Consult | 703-553-1099
When a government contractor is pursuing a cost-type contract, one of the first steps is confirming that their accounting system meets DCAA requirements. That process, a preaward survey conducted by the Defense Contract Audit Agency, evaluates whether the contractor’s system is adequate to support cost-type work.
At Wendroff & Associates, CPA, reviewing accounting systems for DCAA compliance is a routine part of our work with government contracting clients. This article outlines what that review typically involves, the gaps we encounter most frequently, and what contractors and CPAs should understand about building a compliant system.
When we begin a system review, a few key elements give us an immediate picture of where things stand.
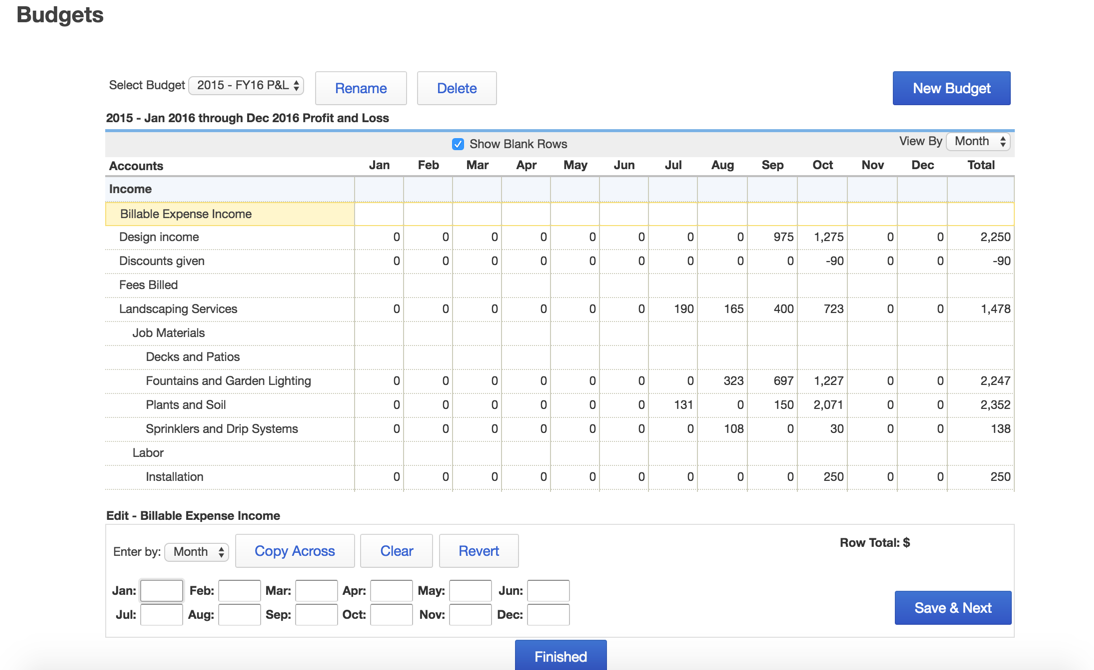
Chart of accounts structure. A well-structured chart of accounts for government contracting separates direct costs from indirect costs and maintains distinct accounts for each indirect pool — Fringe, Overhead, and G&A — as well as a separate account for unallowable costs. The structure of the chart of accounts indicates whether cost segregation requirements are likely being met.
Class or project tracking. DCAA requires that direct costs be tracked by contract. In most accounting systems, this is accomplished through classes or projects. If contracts are not set up as classes or projects — or if they are tracked as line items within the chart of accounts instead — the profit-and-loss-by-contract view that DCAA expects may not be available.
Basis of accounting. DCAA requires accrual-basis accounting. Contractors running on a cash basis will need to convert before a preaward survey can be completed successfully.
These three areas provide an initial indication of how the system is structured and what additional review may be needed.
A common scenario we encounter involves contractors who have been doing government work for some time, are using QuickBooks Online, and have set up a chart of accounts based on a GovCon template. The structure may be a reasonable starting point, but several critical elements are often missing.
Labor distribution may not have been configured. Time may be tracked in a spreadsheet rather than a system that produces an audit trail. Paid leave — vacation, holidays, sick time — may be charged directly to contracts rather than to the Fringe pool. Indirect rate calculations may not have been performed. And written policies for timekeeping and cost allocation may not exist or may not accurately reflect current practice.
These are fixable gaps. Identifying them early, ideally before a cost-type contract is awarded, allows time to address them systematically rather than under deadline pressure.
Across our work with government contracting clients, four gaps appear consistently, regardless of the software being used or the size of the contractor.
1. Labor distribution is incomplete or not configured
Labor distribution is the process of converting approved hours into dollar amounts charged to contracts and indirect pools. It requires calculating the actual hourly rate for each employee for the period, allocating hours to each cost objective, and reconciling the total to payroll — to the penny, each pay period.
A common issue is that paid leave — vacation, holiday, and sick time — is included in direct labor charges rather than allocated to the Fringe pool. Another frequent issue is the use of simplified formulas that do not follow the correct methodology. Both create discrepancies that can be identified during an audit.
2. Timekeeping does not meet DCAA standards
DCAA’s timekeeping requirements are specific. Employees must record time daily, timesheets must be certified by the employee and approved by a supervisor with direct knowledge of the work performed, and all changes must be documented in a tamper-evident audit trail.
Many general-purpose time tracking tools — including QuickBooks’ built-in time tracking — do not meet these requirements. Contractors using these tools may believe their timekeeping is compliant when it does not satisfy the criteria DCAA evaluates during a floor check or preaward survey.
3. Written policies are absent or do not reflect actual practice
DCAA auditors review not only the accounting system but also the written policies that govern how it operates. A timekeeping policy, an indirect rate methodology document, and an unallowable cost identification procedure are all expected to exist and to accurately describe what the contractor does in practice.
These documents do not need to be lengthy. However, they must exist and must be consistent with the system’s actual operation. A well-configured system without supporting documentation may still result in deficiencies during a survey.
4. Cost segregation gaps in the chart of accounts
Direct costs, indirect cost pools (Fringe, Overhead, and G&A), and unallowable costs must be clearly separated in the chart of accounts. In practice, many contractors start with a flat or commercial-style chart of accounts that does not maintain this segregation — for example, employee benefits posted to general expense accounts rather than a defined Fringe pool, or unallowable costs sitting alongside allowable ones in the same account.
These gaps are foundational. Indirect rate calculations cannot be performed accurately when the underlying cost pools are not properly defined, and discrepancies surface quickly when an auditor samples transactions across pools.
Want to check where your system stands? Take our free DCAA Readiness Self-Assessment — 9 questions built around the SF-1408 criteria, with your gaps prioritized.
Contractors whose systems successfully pass DCAA preaward surveys tend to share a few common characteristics.
The system was set up before it was needed. Contractors who establish a compliant accounting structure before pursuing cost-type contracts are generally better positioned when a contracting officer requests a survey. Retrofitting a system under time pressure is more difficult and more costly than building it correctly from the start.
Compliance is treated as ongoing practice, not a one-time event. Contractors who run labor distribution each pay period, maintain their timekeeping policies, and reconcile their books regularly are in a stronger position than those who address these requirements only when an audit is anticipated.
The right tools are in place. Spreadsheet-based labor distribution can work at very small scale, but it becomes difficult to maintain as a company grows. Contractors who use systems designed for DCAA compliance, including tools that automate labor distribution calculations and generate the required audit trails, generally have fewer gaps when a review occurs.
For small and mid-sized contractors on QuickBooks Online, WiseCost is a compliance layer that integrates directly with QBO and adds the functions required for DCAA compliance: timekeeping with audit trails, timesheet approval workflows, automated labor distribution, and journal entry posting to QBO’s general ledger.
For contractors who are not ready to transition to an enterprise ERP, this type of integration can provide a practical path to a compliant system without replacing the accounting software already in use.
DCAA compliance requirements are well-documented, and the gaps we encounter in practice are consistently addressable. The contractors best positioned to navigate preaward surveys are those who understand the requirements early, establish compliant systems before they are needed, and maintain them as an ongoing part of their operations.
For a detailed breakdown of every SF-1408 criterion and what auditors evaluate during a preaward survey, see The Complete Guide to DCAA-Compliant Accounting Systems for Government Contractors on the WiseCost blog.
If you have questions about your accounting system or are preparing for a DCAA preaward survey, please use the Free Consultation button below to speak with a member of our team.