Request a Consult | 703-553-1099
Listen to the Audio Overview
Originally Published: January 2026 | Last Updated: June 2026
Since this article was originally published in January 2026, several important rollout details have become clearer as the July 4, 2026 launch date approaches.
Recent reporting indicates that the federal government’s one-time $1,000 contribution for eligible children is expected to begin around the July 4 launch window. However, the payment is not automatic. Parents or guardians must first properly establish the account and make the required IRS election on the child’s behalf.
The U.S. Treasury has launched the official Trump Accounts app ahead of the July 4 rollout. Parents and guardians who have already made the required IRS election may receive phased activation emails with instructions to set up their accounts. The app is available through Apple’s App Store, Google Play, and TrumpAccounts.gov.
The IRS now allows taxpayers to view and submit Trump Account elections through their IRS Individual Account. Families who already filed Form 4547 may be able to track the status of their election online.
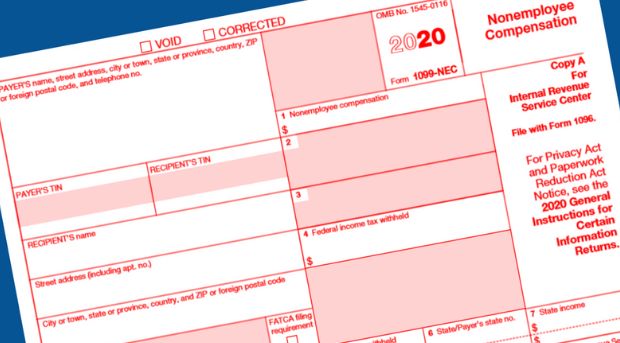
Parents and guardians who have not yet made the election should note that Form 4547 is used both to request creation of a Trump Account and, for eligible children, to request the one-time $1,000 federal pilot program contribution.
Although families may make the required election before then, contributions to Trump Accounts — including the federal pilot contribution — cannot begin before July 4, 2026.
Treasury has indicated that activation emails will come from no-reply@TrumpAccounts.Treasury.gov. The agency has also stated that it will not contact families by text message or phone call about account activation. If you receive a text or phone call claiming to activate a Trump Account, it is likely a scam.
Originally Published: January 2026
In 2026, families will have a new way to save and invest for their children’s future: the 530A account, commonly known as a Trump Account. Created under the One Big Beautiful Bill Act (OBBBA), this tax-advantaged account is designed specifically for minors and provides a structured way for families to invest on their child’s behalf.
As part of the rollout, parents and guardians may make the required IRS election for a Trump Account on their 2025 tax return, even though accounts cannot be funded until July 2026. Additional IRS guidance is expected regarding the final mechanics of the election and account activation.
For families focused on long-term planning, these accounts can help children enter adulthood with greater financial security and an early understanding of saving and investing.
A Trump Account is a new type of tax-advantaged retirement account established for a child. The account is owned by the child but administered by a parent or legal guardian while the child is a minor. It is structured as a custodial-style traditional IRA and is intended to support long-term saving and investing rather than short-term spending.
Children under age 18 with a Social Security number are eligible. Only one Trump Account may be established per child.
Trump Accounts are becoming available in 2026, with contributions permitted as of July 4, 2026. Parents or legal guardians can establish an account by making an election with the IRS on their 2025 tax return using Form 4547. The election may be filed either by attaching the form to a paper return or by e-filing. In the future, accounts may also be set up using the IRS’s online portal at trumpaccounts.gov once finalized.
After the election is made, the Treasury Department will provide instructions to activate the account. Additional guidance is expected as more financial institutions begin offering Trump Accounts.
Contributions to a Trump Account may be made by:
Total personal and employer contributions are capped at $5,000 per child per year, and the child does not need earned income to participate. Employer contributions, where available, may be made directly or through payroll elections and will depend on the employer’s specific plan.
In addition, the federal government will make a one-time $1,000 seed contribution for eligible U.S. citizen children born between January 1, 2025, and December 31, 2028. This government contribution, along with certain state, government entity, and other charitable contributions, does not count toward the annual limit.
Individual contributions are made on an after-tax basis, meaning the contribution amount itself is not taxed when withdrawn. Contributions from employers, government entities, or charitable organizations are generally made on a pre-tax basis and are taxable when distributed. Regardless of source, earnings on all contributions grow tax-deferred until funds are withdrawn.
Funds must be invested in certain low-cost mutual funds or exchange-traded funds that track broad U.S. stock market indexes. The investment options are intentionally limited to keep costs low and focus on long-term growth, rather than short-term trading or complex strategies.
Trump Accounts are designed for long-term growth, and withdrawals are generally not permitted while the child is a minor. This growth period lasts until the year the child turns 18. Beginning that year, the account generally follows the same withdrawal rules as a traditional IRA, and distributions may be subject to income tax and potential penalties unless an exception applies.
One important distinction is that a Trump Account can remain separate from other IRAs after age 18, which may provide additional flexibility for future planning. Additional details regarding withdrawal exceptions and coordination with other retirement accounts are expected in future IRS guidance.
Trump Accounts are designed to work alongside, not replace, other child savings tools. Options such as 529 plans and Roth IRAs (for children with earned income) may still play an important role, depending on a family’s goals. Whether a Trump Account makes sense will depend on timing, long-term priorities, and how a family anticipates using funds as a child gets older.
We will continue to monitor developments related to the rollout of Trump Accounts and share updates with our clients. If you’d like help thinking through how a Trump Account might fit into your family’s tax planning strategy, please use the FREE CONSULT button below to speak with a member of our team.