Request a Consult | 703-553-1099
Law firm accounting is a nuanced process with ethical, operational, and regulatory requirements that many other businesses do not face. From managing trust accounts to tracking billable hours and accurately recognizing revenue, legal accounting requires planning and in-depth industry knowledge.
Wendroff & Associates, CPA has nearly two decades of experience providing expert tax and accounting services to legal professionals, from solo practitioners to regional firms across DC, Virginia, and Maryland.
Below, we break down the essential accounting practices for law firms, along with examples and insider tips from our team to help you avoid compliance pitfalls and improve financial performance.
One of the most important distinctions is the handling of client funds. Law firms must use a dedicated trust account, often referred to as an IOLTA (Interest on Lawyers’ Trust Account), to hold client retainers or settlement funds. These funds legally belong to the client until earned and must never be commingled with the firm’s operating funds.
Example: A personal injury lawyer receives a $10,000 settlement check for a client. That money must be deposited in the firm’s IOLTA account. Only after deducting agreed-upon legal fees and disbursing the remainder to the client can the firm transfer its portion to the operating account.
Wendroff Insight: Mismanaging trust funds can lead to severe disciplinary action, including disbarment. Law firms must maintain meticulous records, including three-way reconciliations between the bank balance, the trust ledger, and individual client ledgers.
Law firms often receive retainers or prepayments, which can’t be counted as income until the work is performed. Additionally, firms may work on contingency arrangements or charge flat or hourly fees, each of which affects how and when revenue is recognized.
Example: A family law attorney collects a $5,000 retainer upfront. Even though the funds are in the trust account, they can’t be counted as income until legal services are rendered. If $2,000 worth of work is completed in the first month, only that portion can be moved to income and removed from trust.
Wendroff Insight: Recognizing revenue before it’s earned can lead to inflated income, tax issues, or even ethical violations. Clear processes are needed to track unearned income and release it appropriately.
While many firms file taxes on a cash basis, they may use accrual accounting internally to better track billings, work in progress (WIP), and collections.
Example: Your firm may operate on a cash basis for tax filing, meaning you only pay taxes on income once it’s received. However, you can still track all billable time and expenses in an accrual-based practice management system, such as Clio, to obtain a complete financial picture.
Wendroff Insight: This hybrid approach provides a more comprehensive view of financial health, but it necessitates a deeper understanding of both methods to manage effectively.
As previously mentioned, law firms track WIP billable time that has been recorded but not yet billed to clients. Although not technically income, WIP represents a significant financial asset and should be closely monitored.
Example: If your firm logged 15 hours of billable time for a small business client this month but hasn’t sent an invoice yet, that time is considered WIP. It’s not presently considered income, but it represents value the firm has created and will bill in the near future.
Wendroff Insight: Failure to track WIP can result in lost revenue and inaccurate performance metrics. It also affects cash flow forecasting and compensation planning.
Law firms often have complex compensation models based on equity, performance, or origination volume. Additionally, partners often have capital accounts that must be tracked over time.
Example: Two partners may agree to split profits 60/40 based on originations. If Partner A brings in most of the clients but Partner B bills more hours, the compensation structure must be clear, and draws and equity must be tracked accurately.
Wendroff Insight: Proper accounting for draws, distributions, and equity changes is essential for maintaining transparency and effective partnership management.
Client-related costs such as court filing fees, expert witness expenses, and travel are often reimbursable or billable. These expenses must be tracked by client or matter for accurate invoicing and compliance.
Example: If your firm pays a $300 court filing fee on behalf of a client, that should be coded to that specific matter in your accounting system so it can be included in the client’s next invoice and not mistakenly absorbed as overhead.
Wendroff Pro Tip: Without proper allocation, firms risk underbilling or violating ethical guidelines related to client reimbursements.
State bar associations and the ABA impose strict rules governing the management of legal funds and financial records. These rules extend far beyond general business practices.
Wendroff Insight: Noncompliance can damage your firm’s reputation and result in financial penalties or loss of licensure. Legal accounting is as much about ethics as it is about finance.
Because of the complexity of law firm finances, general-purpose accounting software often falls short. Legal-specific platforms, such as Clio, LEAP, and CosmoLex, integrate timekeeping, billing, trust accounting, and compliance tools tailored to the specific needs of law practices.
However, tools like Clio are not full accounting systems. They don’t include a general ledger or chart of accounts. For complete financial reporting, Clio is often paired with accounting software like QuickBooks Online, which can generate profit and loss statements, balance sheets, and tax-ready reports.
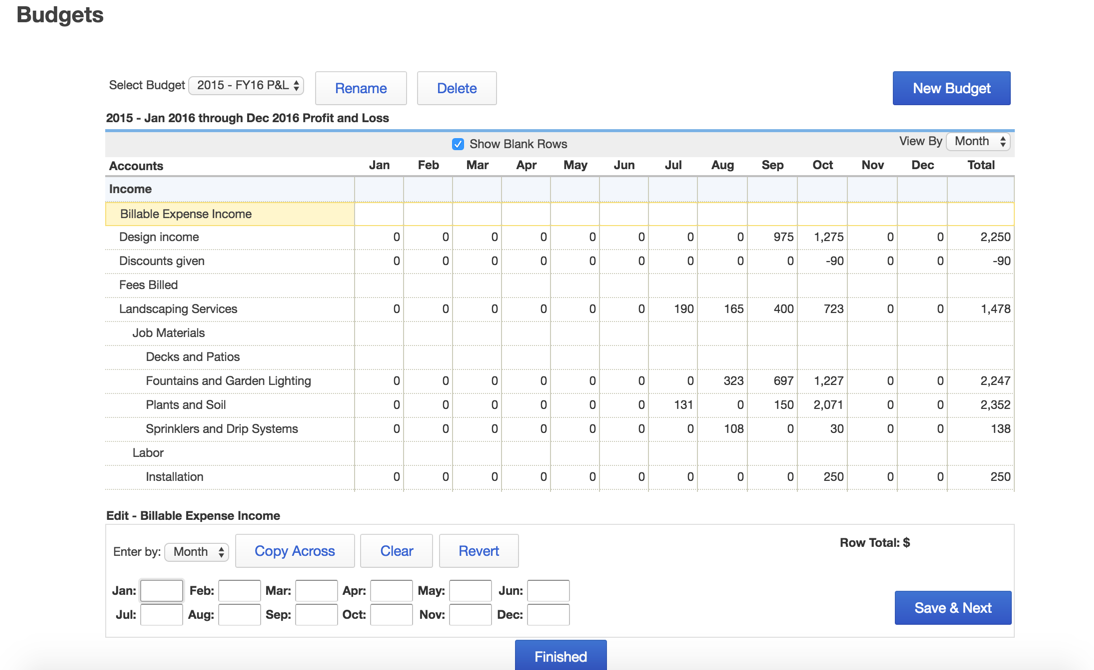
To make the most of these integrations, it’s important to use a well-structured chart of accounts designed specifically for law firms.
Download our Law Firm Chart of Accounts template for use with QuickBooks Online, and learn more about how to structure and customize it in our article, How to Create a Chart of Accounts for a Law Firm.
DOWNLOAD TEMPLATEWendroff Insight: The right tools reduce human error, streamline billing, and support compliance with trust accounting rules, especially when paired with expert setup and accounting oversight.
While these best practices offer a strong foundation, law firm accounting is complex, and mistakes can be costly. From trust compliance to revenue recognition and WIP tracking, even small oversights can create big risks for your practice.
The most effective way to ensure long-term financial health is to work with an accounting firm that understands the unique demands of the legal profession. Our team knows what sets law firms apart and how to support your goals at every stage of growth.
Have questions or ready to take the next step? Use the Free Consultation button below to connect with our team.